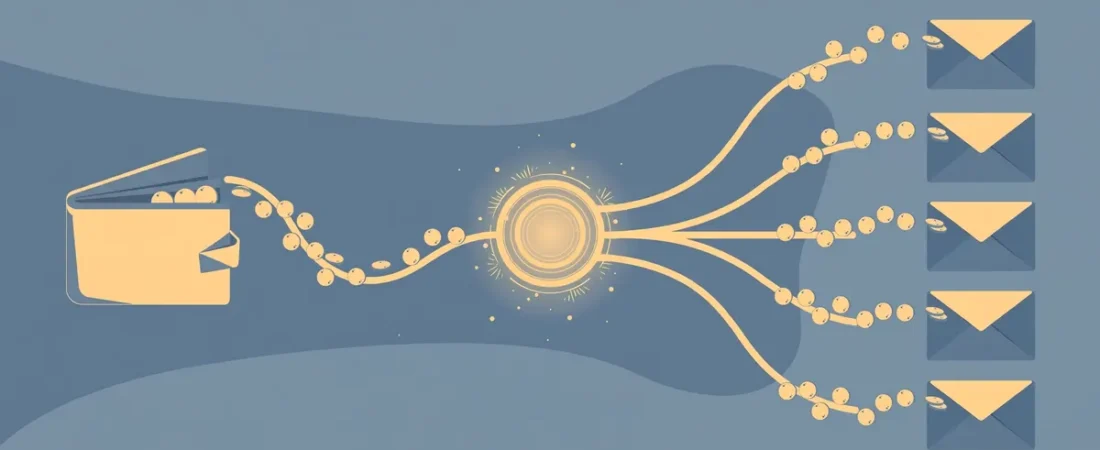
A Debt Management Plan — usually called a DMP — is the main program nonprofit credit counseling agencies offer. It's not a loan, and it's not a negotiation to pay less than you owe. It's a structured repayment plan: you make one monthly payment to the counseling agency, the agency distributes it to your creditors, and in exchange the creditors typically agree to lower your interest rates and waive certain fees.
The single most important thing to understand: in a DMP, you repay your principal in full — 100% of what you borrowed. What changes is the interest rate and the structure, not the amount owed. That distinction is what separates a DMP from debt settlement, where the goal is to pay less than the full balance.
This guide walks through the mechanics, the real costs, the timeline, and what happens step by step — so you can decide with your eyes open. If you haven't read it yet, start with What Is Credit Counseling? to understand the free session that comes before any of this.
The core idea, in plain language
Imagine you have five credit cards with balances totaling $20,000, interest rates between 19% and 29%, and five different due dates. Every month, a big chunk of your payments goes to interest, and the balances barely move.
A DMP reorganizes that situation into one agreement:
- You make one monthly payment to the nonprofit agency.
- The agency distributes that payment to each of your creditors on an agreed schedule.
- Creditors who agree to the plan lower your interest rates and often stop late fees and over-limit fees.
- You pay on that schedule for 36 to 60 months (3 to 5 years), per NFCC guidance as of 2026.
- At the end, the enrolled debts are paid off — principal in full.
You still owe your original creditors the whole time. The agency is the administrator and negotiator, not the lender. There is no new loan to qualify for and no credit check to enroll.
Step by step: how a DMP actually works
### Step 1: The counseling session
Everything starts with the free credit counseling session — a full review of your income, expenses, debts, and credit reports. The counselor determines whether a DMP fits your situation. It doesn't fit everyone: you need enough steady income to cover the monthly payment, and your debts need to be mostly the unsecured kind the plan is built for (credit cards, some medical bills, certain personal loans). If a DMP isn't right, a legitimate counselor will say so and discuss other options.
### Step 2: The proposal
If a DMP looks workable, the agency drafts a written proposal: every enrolled account, the proposed monthly payment to each creditor, the negotiated interest rates and fee treatment, and the estimated plan length. Get this in writing before you agree to anything. It should name each creditor, each account, and the exact numbers — not vague promises.
### Step 3: Creditor approval
The agency sends the proposal to your creditors. Participation is voluntary — creditors choose whether to accept the plan and what concessions to offer. Most major credit card issuers have longstanding relationships with nonprofit agencies and routinely agree to reduced rates, but terms vary by creditor. Your counselor should tell you honestly which of your creditors typically cooperate and which don't.
### Step 4: You make one payment; the agency pays everyone
Once creditors accept, you begin making a single monthly payment to the agency — usually by automatic bank draft. The agency disburses the funds to your creditors according to the plan. You get one statement, one due date, one payment.
### Step 5: Accounts are brought current and closed
Enrolled credit card accounts are typically frozen or closed — you'll be asked to stop using them, and most issuers close the accounts once the balance is paid off. You generally can't open new credit cards while enrolled (mortgages and auto loans are usually still allowed). On-time DMP payments can bring past-due accounts current, often within about three payments, according to industry guidance.
### Step 6: Completion
Make every payment, don't take on new debt, and at the end of the plan the enrolled balances are zero. There are no prepayment penalties — if you come into extra money, you can pay the plan off early.
What it costs: fees, honestly
The counseling session is free. The DMP itself carries fees — modest ones, but you should know them before enrolling.
- Setup/enrollment fee: typically around $25 to $75, one time. Some agencies charge less; a few charge nothing.
- Monthly maintenance fee: typically around $25 to $55 per month, though published ranges run from about $20 to $75 depending on the agency and state.
- Fee caps vary by state. Many states cap what agencies can charge, and caps differ — there is no single national number for nonprofit DMP fees. Reputable agencies keep fees low, and NFCC standards call for fees to remain as low as possible.
- Hardship waivers are common. Many agencies reduce or waive fees for very low-income clients, military members, veterans, and people affected by disasters. Counseling cannot be refused solely because you can't pay.
Always ask for the written fee schedule before enrolling, and confirm whether the monthly fee is included in your quoted payment or added on top. A legitimate agency answers these questions plainly.
How long it takes: the 36-to-60-month timeline
Most DMPs run three to five years (36 to 60 months), per NFCC guidance. The exact length depends on your total enrolled debt and the size of your monthly payment. Some plans run slightly longer — debt.org notes that reputable nonprofit plans typically take 3 to 6 years — but the 36-to-60-month range is the standard expectation as of 2026.
Why so long? Because you're repaying the full principal. The lower interest rates are what make the timeline achievable: less of each payment is consumed by interest, so more of it reduces the balance. Your agency is required by NFCC standards to give you a reliable estimate of plan length and to check that the payment fits your budget before the plan is set up — a payment you can't sustain is a plan designed to fail.
The interest-rate question: what "negotiated lower rates" really means
This is where honest expectations matter most. Creditors routinely agree to reduce interest rates on DMP accounts — often substantially. Published estimates vary: Experian-cited figures put negotiated DMP rates anywhere from 0% to around 9%, while other industry sources cite a 0% to roughly 11% range. Your actual rates depend on each creditor's concession policies and your account history.
What that means in practice: a card at 24% might drop to 8%, 6%, or in some cases lower. The agency cannot promise any specific rate before creditors respond to the proposal. If anyone quotes you exact final rates before creditor approval, treat that as a red flag, not a feature.
A worked example (illustrative, with stated assumptions)
Because real numbers help, here's an illustration — not a promise, and not your situation. Assumptions: $18,000 in credit card debt across four cards, average interest rate 22%, minimum payments totaling about $540/month, and a DMP that negotiates the average rate down to 7% with a $35 monthly agency fee.
- On minimums alone at 22%: the payoff stretches many years, with total interest running into the many thousands.
- On a DMP at 7% with a single payment of about $540/month: the balance clears in roughly 40 months, with total interest of a few thousand dollars plus about $1,400 in agency fees over the life of the plan.
The savings come almost entirely from the interest-rate reduction. The fees are real but small relative to the interest avoided. Your numbers will differ — ask your counselor to show you the same math for your actual accounts before you enroll.
What a DMP does to your credit
The honest version has two parts:
- The counseling session itself: zero impact. No inquiry, no notation, nothing on your report.
- Enrolling in the DMP: a notation may appear on your credit report indicating accounts are being paid through a credit counseling program. That notation itself is not factored into FICO or VantageScore calculations. What does affect your score: on-time payments (positive — payment history is 35% of a FICO score), and closed accounts (closing enrolled cards can cause a small temporary dip by changing your credit utilization and account age).
Over the life of a successfully completed plan, consistent on-time payments generally move scores in the right direction. The accounts most likely to hurt you in a DMP are the ones you stop paying — so the payment has to fit your budget from day one.
What happens if you drop out
This deserves its own section, because it's the part nobody puts in the brochure. A DMP is voluntary, and you can leave at any time. But leaving has consequences:
- Creditor concessions typically revert — interest rates go back up, and waived fees can return.
- Accounts you stopped paying during the plan (if any) are now further behind.
- You've paid monthly fees for months without reaching the payoff.
This is why affordability screening matters so much. Before signing, ask the agency directly: What exactly happens to my accounts and my rates if I leave the plan in month 14? A good counselor answers that question without flinching. For the full ledger of trade-offs, read DMP Pros and Cons: The Honest Trade-offs Nobody Mentions.
DMP vs. debt settlement: the one-paragraph version
A DMP repays 100% of principal with reduced interest, modest fees, and generally neutral-to-positive credit effects. Debt settlement aims to pay less than the full balance — typically with fees of 20–25% of enrolled debt, significant credit damage from deliberately delinquent accounts, and possible tax consequences on forgiven amounts. They're different tools for different situations, not competitors on the same shelf. Our full comparison is at Debt Settlement vs. Debt Management Plan.
The bottom line
A debt management plan is a disciplined, full-repayment path: one monthly payment to a nonprofit agency, negotiated lower interest rates, a 36-to-60-month timeline, and modest fees with hardship waivers available. It works best for people with steady income and mostly credit card debt who can commit to several years of consistent payments — and who understand exactly what happens if they can't. Before you sign anything, read the trade-offs piece next.
DebtRelief.site publishes general educational information only — not financial, legal, or tax advice. Consider speaking with a qualified professional about your situation.